iFANN
    iFANNを検索...
    ログイン
    ホーム
    ニュース
    動画
    写真
    GIF
    見つける
    投票
    アワード
    iFAMOUS
    ウィキ
    アニメ
    ルーム
    通知
    メッセージ
    ブックマーク
    プロフィール
    ウィキアワードiFAMOUSランキング業界クリエイター報酬ユーザー報酬利用規約プライバシーコミュニティガイドライン削除申請 / DMCAヘルプ開発者

    © 2026 iFANN

    ホーム
    検索
    メッセージ
    お知らせ
    プロフィール
    写真
    Tim Official
    Tim Official@tim_official1w
    🏛️Federal Reserve💭Finance💭Investing
    Private credit valuations and the 11 cent collapse

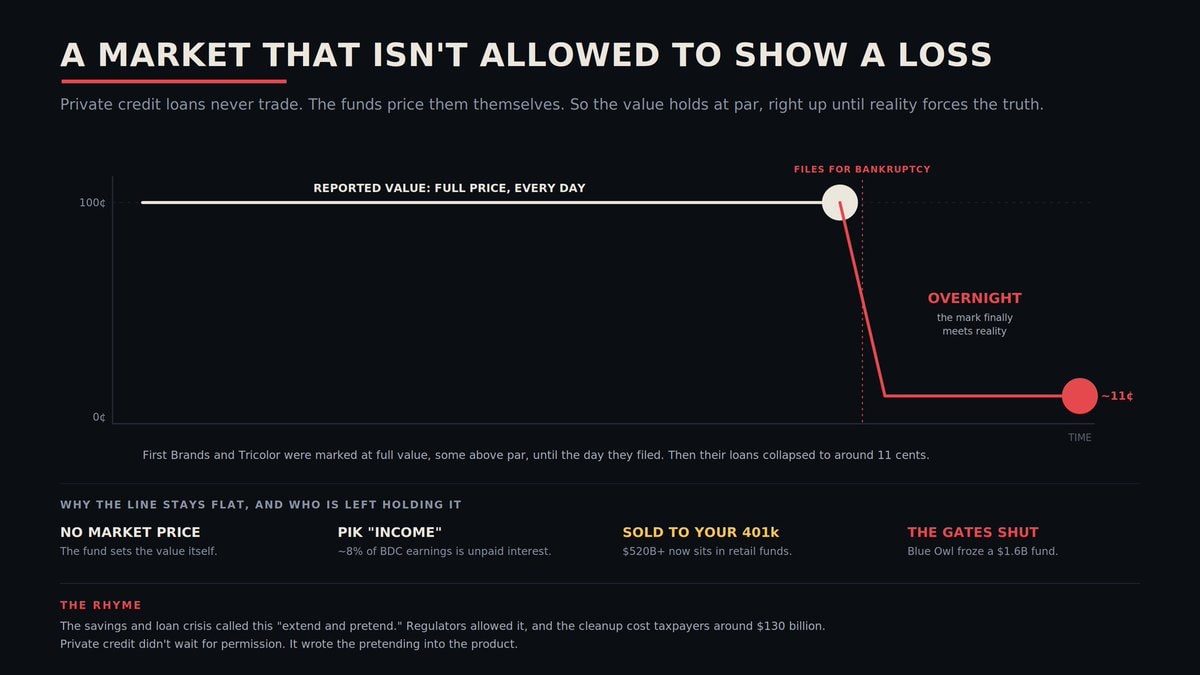
    @tim_officialA $1.7 trillion market where nothing ever goes down on paper isn't a market, it's a promise. And promises get priced by the person who owes you. Wall Street has spent two years bracing for private credit to go full 2008. The comparison misses the mechanism. Back then the mortgage bonds were publicly traded, so when they turned toxic the price fell where everyone could see it and the system had to respond within months. These loans never trade. The fund that holds them runs its own models and decides what they're worth. Federal Reserve researchers found those marks parked near full value while the companies behind them kept weakening. First Brands and Tricolor showed how that resolves. Both sat at full price, a couple above it, until the day they filed. Then the loans went to roughly 11 cents on the dollar. Overnight. On paper. The paper had been lying the whole way down. A return that never dips is the sales pitch. It's also the tell. No manager marks a loan down until a bankruptcy forces the number. Then there's the part that makes it hard to argue with. A borrower short on interest doesn't have to pay cash. The interest gets bolted onto the debt instead, an IOU everyone knows won't be honored. The fund books that IOU as earnings and in many cases distributes it to investors. About 8% of what these funds report as earnings is that phantom money. 90% of managers expect it to grow this year. Default numbers stay calm while the borrowers underneath rot. We've run this play before. 2008 is the reflex, but the 1980s savings and loan crisis fits better. Insolvent lenders kept fake values on their books instead of admitting losses, a policy politely called "extend and pretend." That delay turned a manageable problem into a taxpayer bailout of around $130 billion. Private credit didn't need a regulator to permit the pretending. The pretending is built into the product. The manager sets the value, so a rotten loan stays at full price until a courtroom says otherwise. For a decade this was pensions and endowments, institutions that knew they were buying illiquid, hard-to-price loans and could wait ten years. Those buyers are full. So the managers need a new pool of money, and they found it: you. The same loans are being repackaged into funds sold to ordinary investors, and the door to your 401k was pried open. More than half a trillion dollars already sits in these retail products. And it's arriving at the worst possible moment. Defaults are climbing, and some funds have already frozen the exits. One Blue Owl fund holding $1.6 billion permanently stopped letting investors pull their money out. That's the trap built into these products. The doors lock at the exact moment everyone tries to leave at once. Wall Street will tell you the recent blowups were isolated frauds and the smooth returns are real. Some of that may be true. But a return you cannot sell, cannot verify, and cannot exit is only a promise, and it's priced by the person who owes it to you. So stop waiting for the crash. There isn't going to be one. The loss will show up years from now as a line in retirement statements that simply stopped growing, long after the people who sold it have collected their fees and moved on.

    元の投稿を見る
    Private credit valuations and the 11 cent collapse

    @tim_officialさんの写真· Sep 25, 2026· Federal Reserve

    この写真について

    This is a dark-themed infographic illustrating a financial concept. A line graph shows a value starting at 100 cents and remaining flat until a sharp drop to approximately 11 cents, labeled "OVERNIGHT the mark finally meets reality." Text overlays explain the scenario of private credit loans and their collapse. The overall mood is serious and informative, typical of financial analysis or news. A notable detail is the stark red line representing the dramatic loss. ON-SCREEN TEXT: A MARKET THAT ISN'T ALLOWED TO SHOW A LOSS REPORTED VALUE: FULL PRICE, EVERY DAY FILES FOR BANKRUPTCY OVERNIGHT the mark finally meets reality ~11¢ TIME First Brands and Tricolor were marked at full value, some above par, until the day they filed. Then their loans collapsed to around 11 cents. WHY THE LINE STAYS FLAT, AND WHO IS LEFT HOLDING IT NO MARKET PRICE The fund sets the value itself. PIK "INCOME" ~8% of BDC earnings

    Federal Reserveの写真をすべて見るFederal Reserveのウィキを読む

    ?

    まだコメントはありません。最初のコメントを投稿しましょう!

    Federal Reserveの写真をもっと見る

    Federal Reserveの写真をすべて見る
    Federal Reserve official blackmail allegation2Federal Reserve official blackmail allegationTrump on Jerome Powell Federal Reserve2Trump on Jerome Powell Federal ReserveFederal Reserve FOMC projection update2Federal Reserve FOMC projection updateFed asks if AI is too big to failFed asks if AI is too big to failCrypto market heatmap with Bitcoin and Ethereum gainsCrypto market heatmap with Bitcoin and Ethereum gainsFederal Reserve interest rate forecast2Federal Reserve interest rate forecastPresident Trump slams Fed rate hikePresident Trump slams Fed rate hikeFed rate hike announcementFed rate hike announcementFederal Reserve rate hikeFederal Reserve rate hikeFederal Reserve Kevin Warsh inflation statementFederal Reserve Kevin Warsh inflation statementBrent crude price graph3Brent crude price graphFederal Reserve interest rates2Federal Reserve interest ratesUS inflation gas prices Fed rate hike odds3US inflation gas prices Fed rate hike oddsFederal Reserve interest rates PPI2Federal Reserve interest rates PPIFederal Reserve interest rate forecast2Federal Reserve interest rate forecastTrump jobs August interest ratesTrump jobs August interest ratesFederal Reserve September rate hike projection2Federal Reserve September rate hike projectionFederal Reserve interest rate odds2Federal Reserve interest rate odds
    写真
    Tim Official
    Tim Official@tim_official1w
    🏛️Federal Reserve💭Finance💭Investing
    Private credit valuations and the 11 cent collapse

    @tim_officialA $1.7 trillion market where nothing ever goes down on paper isn't a market, it's a promise. And promises get priced by the person who owes you. Wall Street has spent two years bracing for private credit to go full 2008. The comparison misses the mechanism. Back then the mortgage bonds were publicly traded, so when they turned toxic the price fell where everyone could see it and the system had to respond within months. These loans never trade. The fund that holds them runs its own models and decides what they're worth. Federal Reserve researchers found those marks parked near full value while the companies behind them kept weakening. First Brands and Tricolor showed how that resolves. Both sat at full price, a couple above it, until the day they filed. Then the loans went to roughly 11 cents on the dollar. Overnight. On paper. The paper had been lying the whole way down. A return that never dips is the sales pitch. It's also the tell. No manager marks a loan down until a bankruptcy forces the number. Then there's the part that makes it hard to argue with. A borrower short on interest doesn't have to pay cash. The interest gets bolted onto the debt instead, an IOU everyone knows won't be honored. The fund books that IOU as earnings and in many cases distributes it to investors. About 8% of what these funds report as earnings is that phantom money. 90% of managers expect it to grow this year. Default numbers stay calm while the borrowers underneath rot. We've run this play before. 2008 is the reflex, but the 1980s savings and loan crisis fits better. Insolvent lenders kept fake values on their books instead of admitting losses, a policy politely called "extend and pretend." That delay turned a manageable problem into a taxpayer bailout of around $130 billion. Private credit didn't need a regulator to permit the pretending. The pretending is built into the product. The manager sets the value, so a rotten loan stays at full price until a courtroom says otherwise. For a decade this was pensions and endowments, institutions that knew they were buying illiquid, hard-to-price loans and could wait ten years. Those buyers are full. So the managers need a new pool of money, and they found it: you. The same loans are being repackaged into funds sold to ordinary investors, and the door to your 401k was pried open. More than half a trillion dollars already sits in these retail products. And it's arriving at the worst possible moment. Defaults are climbing, and some funds have already frozen the exits. One Blue Owl fund holding $1.6 billion permanently stopped letting investors pull their money out. That's the trap built into these products. The doors lock at the exact moment everyone tries to leave at once. Wall Street will tell you the recent blowups were isolated frauds and the smooth returns are real. Some of that may be true. But a return you cannot sell, cannot verify, and cannot exit is only a promise, and it's priced by the person who owes it to you. So stop waiting for the crash. There isn't going to be one. The loss will show up years from now as a line in retirement statements that simply stopped growing, long after the people who sold it have collected their fees and moved on.

    元の投稿を見る
    Private credit valuations and the 11 cent collapse

    @tim_officialさんの写真· Sep 25, 2026· Federal Reserve

    この写真について

    This is a dark-themed infographic illustrating a financial concept. A line graph shows a value starting at 100 cents and remaining flat until a sharp drop to approximately 11 cents, labeled "OVERNIGHT the mark finally meets reality." Text overlays explain the scenario of private credit loans and their collapse. The overall mood is serious and informative, typical of financial analysis or news. A notable detail is the stark red line representing the dramatic loss. ON-SCREEN TEXT: A MARKET THAT ISN'T ALLOWED TO SHOW A LOSS REPORTED VALUE: FULL PRICE, EVERY DAY FILES FOR BANKRUPTCY OVERNIGHT the mark finally meets reality ~11¢ TIME First Brands and Tricolor were marked at full value, some above par, until the day they filed. Then their loans collapsed to around 11 cents. WHY THE LINE STAYS FLAT, AND WHO IS LEFT HOLDING IT NO MARKET PRICE The fund sets the value itself. PIK "INCOME" ~8% of BDC earnings

    Federal Reserveの写真をすべて見るFederal Reserveのウィキを読む

    ?

    まだコメントはありません。最初のコメントを投稿しましょう!

    Federal Reserveの写真をもっと見る

    Federal Reserveの写真をすべて見る
    Federal Reserve official blackmail allegation2Federal Reserve official blackmail allegationTrump on Jerome Powell Federal Reserve2Trump on Jerome Powell Federal ReserveFederal Reserve FOMC projection update2Federal Reserve FOMC projection updateFed asks if AI is too big to failFed asks if AI is too big to failCrypto market heatmap with Bitcoin and Ethereum gainsCrypto market heatmap with Bitcoin and Ethereum gainsFederal Reserve interest rate forecast2Federal Reserve interest rate forecastPresident Trump slams Fed rate hikePresident Trump slams Fed rate hikeFed rate hike announcementFed rate hike announcementFederal Reserve rate hikeFederal Reserve rate hikeFederal Reserve Kevin Warsh inflation statementFederal Reserve Kevin Warsh inflation statementBrent crude price graph3Brent crude price graphFederal Reserve interest rates2Federal Reserve interest ratesUS inflation gas prices Fed rate hike odds3US inflation gas prices Fed rate hike oddsFederal Reserve interest rates PPI2Federal Reserve interest rates PPIFederal Reserve interest rate forecast2Federal Reserve interest rate forecastTrump jobs August interest ratesTrump jobs August interest ratesFederal Reserve September rate hike projection2Federal Reserve September rate hike projectionFederal Reserve interest rate odds2Federal Reserve interest rate odds